The Federal Poverty Level (FPL) household income guidelines for calendar year 2027
The Open Enrollment Period (OEP) deadlines for every state, including exceptions/special cases
The official ACA Exchange/Marketplaces to use to shop for & enroll in healthcare coverage
The 2027 Advance Premium Tax Credit (APTC) household income table for calculating subsidy eligibility
Ways to legally keep your Modified Adjusted Gross Income (MAGI) below the 400% FPL subsidy eligibility cut-off threshold, and...
A reminder that starting this year, there's no longer any caps on what portion of those subsidies you might have to pay back if your actual MAGI ends up being higher than you anticipated.
(sigh) Welp. Welcome to TrumpCare 2.0: The subsidies have been gutted, anyone earning more than 4x the federal poverty level is completely S.O.L., nearly anyone who isn't a U.S. citizen has been thrown under the bus, and there's more ugliness yet to come.
Even with all of this, however, the ACA isn't quite dead yet: It still offers affordable coverage to many people (if far less affordable than it was a year ago), it still offers a lot of vitally important patient protections, and it's still the only viable option for millions of Americans who are self-employed or who work for small businesses which don't offer decent health coverage on their behalf.
So, with that in mind, it's time once again to update my annual ACA Open Enrollment Period (OEP) Guide for 2027. As I noted last year, most of the Open Enrollment tips I give every year remain good advice, even if they kind of feel like slapping a Band-Aid® on a gaping gunshot wound this year.
ACA exchange enrollment has dropped by 20% in Kansas since Congressional Republicans allowed the enhanced federal subsidies to expire at the end of last year.
Initial signups during Open Enrollment were only down 3.6% vs. OEP 2025...but effectuated enrollment was 9.3% lower year over year in January, rising to 20% lower as of February.
That's over 36,000 Kansans who already lost coverage in just the first two months of the year...a number which has likely continued to climb since then.
Here's what this looks like visually, with both 2025 and 2019 (the last pre-COVID year, which didn't include the enhanced subsidies) included for comparison:
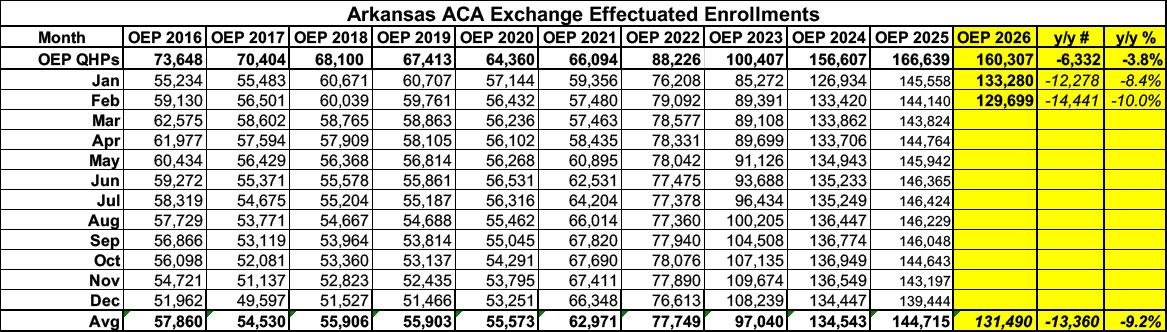
ACA exchange enrollment has dropped by 10% in Arkansas since Congressional Republicans allowed the enhanced federal subsidies to expire at the end of last year.
Initial signups during Open Enrollment were only down 3.8% vs. OEP 2025...but effectuated enrollment was down over 8% year over year in January and by 10% (around 14,000 enrollees) as of February.
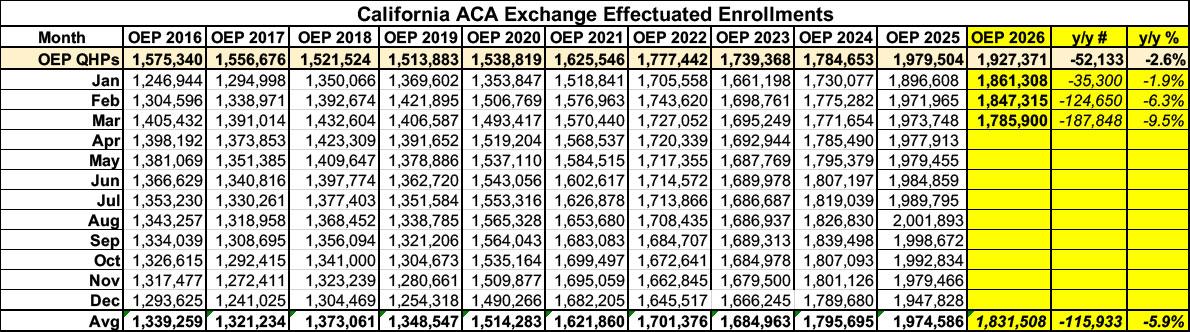
Before I begin, it's important to note that ACA exchange enrollment has dropped in California since Congressional Republicans allowed the enhanced federal subsidies to expire at the end of last year...although thanks to the state providing its own supplemental financial subsidies to partially cancel out the lost federal subsidies, it's not nearly as dramatic a drop-off as in most other states.
Effectuated enrollment was down 9.5% year over year as of March, and has almost certainly continued to drop further since then based on the trend line (see below). That's at least 187,000 fewer Californians enrolled in ACA healthcare coverage this year.
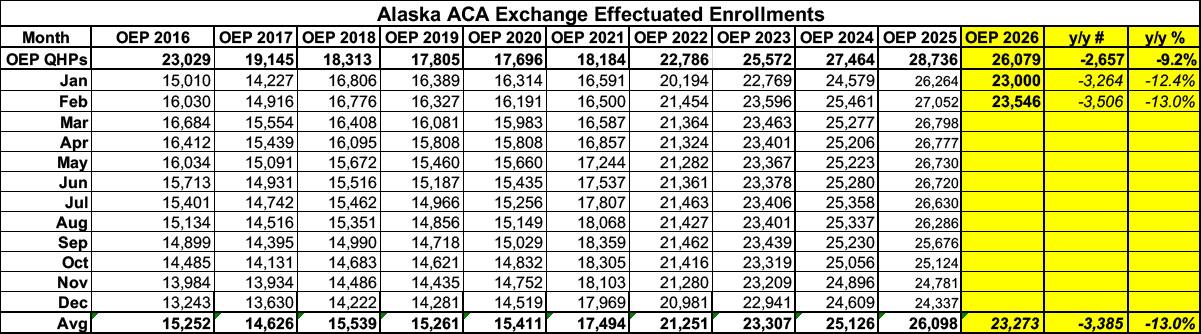
ACA exchange enrollment has dropped significantly in Alaska since Congressional Republicans allowed the enhanced federal subsidies to expire at the end of last year.
Initial signups during Open Enrollment were already down 9.2% vs. OEP 2025...but effectuated enrollment as of January 2026 was down over 12% year over year...increasing to a 13% drop as of February.
The good news, such as it is, is that due to Alaska having such a small ACA population to begin with, this only amounts to around 3,400 people losing coverage...which is small comfort if you're one of those 3,400 people, of course:
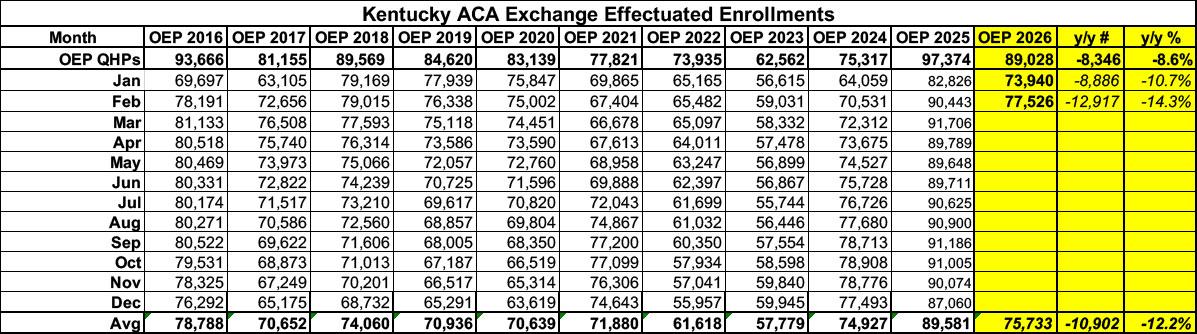
Before I begin, it's important to note that ACA exchange enrollment has dropped significantly in Kentucky since Congressional Republicans allowed the enhanced federal subsidies to expire at the end of last year.
Initial signups during Open Enrollment were down 8.6% vs. OEP 2025...but effectuated enrollment was down nealry 11% in January and over 14% as of February; on average nearly 11,000 Kentuckians lost ACA healthcare coverage in the first two months of 2026:
Here's what this looks like visually, with both 2025 and 2019 (the last pre-COVID year, which didn't include the enhanced subsidies) included for comparison:
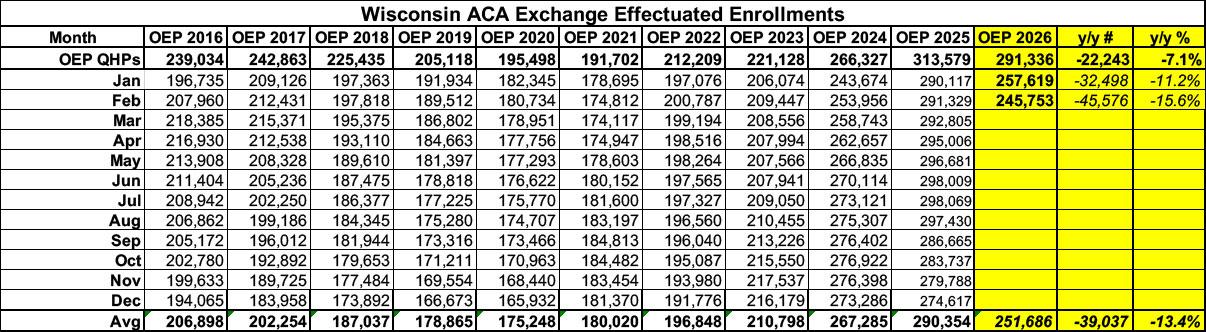
ACA exchange enrollment has dropped by over 15% in Wisconsin since Congressional Republicans allowed the enhanced federal subsidies to expire at the end of last year.
Initial signups during Open Enrollment were down 7% vs. OEP 2025...but effectuated enrollment was 11% lower year over year in January, rising to 15.6% lower as of February.
That's over 45,000 Wisconsinites who already lost coverage in just the first two months of the year...a number which has likely continued to climb since then.
Here's what this looks like visually, with both 2025 and 2019 (the last pre-COVID year, which didn't include the enhanced subsidies) included for comparison:
Medicare Advantage (technically "Medicare Part C" & originally called "Medicare+Choice") is a type of health plan in the United States offered by private companies as part of the original Social Security Act of 1965 that created Medicare. It permits a private insurance option that wraps around traditional Medicare. Medicare Advantage plans attempt to fill some coverage gaps and offer alternative coverage options.
Under Part C, Medicare pays a plan operator a fixed payment for each enrollee. The operator then pays for their medical expenses. Traditional Medicare directly compensates providers on a fee-for-service basis. Plans are offered by integrated health delivery systems, labor unions, non profit charities, and health insurance companies, which may limit enrollment to specific groups of people (such as union members).